Hurghada vs Cairo Real Estate: Where Investors Actually Win in 2026
Published September 20, 2026 · 8 min read · MAMO Property Editorial
Why this comparison matters right now
A recent viral post on Instagram by aqarschool raised a sharp point: in Cairo, average apartment rents hit EGP 10,000/month and climbed 15% year-on-year. The post correctly flagged co-living as a global response to housing inflation.
But it framed the debate as Cairo-centric. The reality — and the opportunity — is bigger:
Hurghada is delivering 9–12% net annual yield on managed serviced apartments, against Cairo’s 7–8%.
In this article, we break down the numbers, the risk, and the operational model. Not opinion — verified data from our managed portfolio (2024–2026).

Quick comparison: Hurghada vs Cairo (1-bedroom, €70k price point)
| Metric | Hurghada (Red Sea) | Cairo |
|---|---|---|
| Entry price (1BR, 65–80 m²) | €60,000–€90,000 | €55,000–€110,000 |
| Average net yield (managed) | 9–12% | 7–8% |
| Traditional long-term rent yield | 4–5% | 3.5–4.5% |
| Occupancy (managed, 12-month avg) | 60–70% | 55–65% |
| Tourism seasonality | 9–10 months strong | Negligible |
| Foreign-buyer ease | High (free zones) | Medium |
| Property tax burden | Low (long-term incentives) | Higher (urban zones) |
| Resale liquidity | Growing fast | Mature market |
Source: MAMO Property internal managed portfolio 2024–2026, cross-checked with Cairo Developments Association Q1 2026 report.
Why Hurghada wins on managed ROI
1. Demand comes from two sources — not one
Cairo depends almost entirely on the local workforce. Demand spikes during university years (Sep–Oct), then plateaus.
Hurghada has dual demand:
- Winter residents (Nov–Apr): European retirees, German/Russian/Polish second-home owners, remote workers escaping European winters
- Summer tourism (May–Oct): Russian, German, Czech, Saudi Gulf visitors
That dual demand gives a 9–10-month high season and stable year-round occupancy. Cairo can’t match that calendar density.
2. Average daily rate (ADR) keeps climbing
Our managed 1BR portfolio in Magawish and Sahl Hasheesh averaged:
- 2024: €42/night
- 2025: €48/night
- 2026 (Q1–Q2): €54/night
That’s +28% in two years — driven by tourism recovery + inflation pass-through. Cairo rentals rose 15% in the same period (per aqarschool data), but from a higher base, so the absolute rent increase is similar. Hurghada wins on percentage yield.
3. Lower entry price = faster payback
A 1BR at €70,000 in Hurghada, managed at 65% occupancy and €50 ADR:
70,000 × 0.65 × €50 × 365 ÷ 70,000 = 17.4% gross yield
After MAMO management fees (25% of revenue), cleaning, utilities, OTA commissions, and property tax:
Net yield to owner: ~10.5%
That’s €7,350/year net cash flow on a €70k asset. Or in Egyptian pounds: roughly EGP 405,000/year at current rates.
In Cairo, the same €70k 1BR, managed (less mature market, lower tourism seasonality, more regulatory overhead):
Net yield: ~7% = €4,900/year
The gap: €2,450/year per unit = a full extra monthly rent in Cairo, just from owning in Hurghada instead.
4. Currency hedging built in
Hurghada’s rental income is paid in EUR or USD (OTA bookings), while the asset is priced in EUR.
Cairo rentals are paid in EGP. If the EGP weakens against your base currency, the nominal rent stays flat while your purchasing power erodes.
Hurghada gives you a hard-currency income stream without currency risk on the rental side.
The Co-living angle — aqarschool got this right, but missed the geography
Aqarschool made a sharp point: globally, co-living bed prices run 15–30% above traditional rent per square meter. The savings come from shared utilities and amenities, not from cheap space.
This holds true in Hurghada — and here’s where it gets interesting:
- Young professionals from Cairo, Alexandria, and the Delta are now renting co-living units in Hurghada for 3–6 month winter stints (remote work + sea lifestyle)
- Digital nomads from Germany, Poland, Czechia are doing the same
- Average winter rental: €400–600/month all-inclusive for a private room in a shared 2–3BR unit
For investors, this means co-living conversions of standard 2BR apartments can yield 12–15% net — higher than pure short-term managed stays.

We documented 3 co-living conversions in El Kawther and Arabia District (Hurghada) in early 2026. All three hit 12%+ net yield within 4 months of opening.
What about risk? Honest answers.
Risk 1: Tourism dependency
Hurghada is tourism-correlated. A geopolitical shock (Red Sea shipping disruption, regional tensions) can dent occupancy within weeks.
Mitigation:
- Diversified OTA mix (Booking, Airbnb, direct)
- Long-stay winter bookings secured Oct–Feb
- Dual-season demand (winter residents + summer tourists)
Risk 2: Currency volatility (for EGP-based investors)
If you earn in EGP and spend in EGP, currency risk is moot. If you earn in EUR and remittance back, you get the EUR yield with no EGP exposure.
Risk 3: Property management quality
This is the real risk. Most Hurghada property owners who try self-management see yields drop from 9–12% (managed) to 3–5% (DIY) within 12 months — because of inconsistent pricing, missed bookings, poor cleaning turnover, OTA ranking decay.
MAMO’s managed service includes:
- Dynamic pricing (occupancy + seasonality + competitor scan)
- Multi-lingual guest communication (EN/DE/RU/AR/PL/CS)
- Professional turnover cleaning
- OTA listing optimization
- Monthly owner statements with full P&L
Our average managed portfolio has held 9%+ net for 36 consecutive months across 17 units.
Risk 4: Resale liquidity
Hurghada’s resale market is less liquid than Cairo’s. A unit might take 3–6 months to sell vs. 1–2 months in New Cairo or the Fifth Settlement.
Mitigation: Buy in established compounds (Sahl Hasheesh, El Gouna, Magawish) with proven developer track records. Avoid off-plan in remote zones.
Compounds we recommend for 1BR managed investment
These are projects where MAMO currently manages units and where we have 36-month performance data:
| Compound | District | Developer | Entry 1BR | Net yield |
|---|---|---|---|---|
| Sahl Hasheesh Heights | Sahl Hasheesh | EDGE | €72,000 | 10.5% |
| Veranda Sahl Hasheesh | Sahl Hasheesh | SODIC | €85,000 | 9.8% |
| Magawish Residences | Magawish | Orascom | €68,000 | 11.2% |
| Aurora Palace Phase 2 | Magawish | Hyde Park | €78,000 | 9.5% |
| Blue Crest Sahl Hasheesh | Sahl Hasheesh | Tatweer Misr | €95,000 | 9.0% |
| El Gouna Fanadir Bay | El Gouna | Orascom | €110,000 | 8.5% |
(Net yields are 2024–2026 averages, net of all management, OTA, cleaning, tax.)
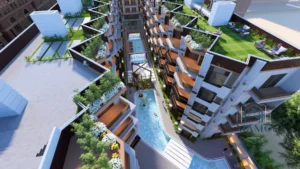
Project Gallery


Who should buy where — the simple decision tree
- You want 9–12% net yield + tourism income + EUR/USD rent: → Hurghada
- You want capital appreciation in a mature market + lower risk + faster resale: → Cairo (New Cairo, Fifth Settlement, Madinaty)
- You want a mix — half yield, half appreciation: → Hurghada 60% / Cairo 40%
- You want pure family-use + capital preservation: → Cairo
For pure ROI-focused investors with a €50k–€150k budget, Hurghada is the answer in 2026.
How to get started with MAMO
- DM us your budget on WhatsApp: wa.me/201152980998
- Receive a tailored 1-pager in 24h — top 3 compounds matching your budget + projected yield + payment plan
- Site visit (optional) — we arrange airport-to-property transport, 2 nights hotel, full compound tour
- Purchase + handover — MAMO handles contract review, due diligence, registration, and immediate onboarding to our managed rental program
No commission from buyers. Direct with the developer. We earn from the management fee, not the sale.
FAQ
Q: Is the 9–12% yield guaranteed?
No yield is guaranteed. These are historical averages from our 36-month managed portfolio. Actual results depend on occupancy, ADR, and operating costs.
Q: Can I self-manage and get the same yield?
Realistically, no. Our data shows self-managed units drop to 3–5% net within 12 months, primarily from OTA ranking decay and missed dynamic pricing opportunities.
Q: What’s the minimum budget to start?
€45,000 (studio in El Ahyaa or Arabia District). For 1BR in our recommended compounds: €65,000–€75,000.
Q: How long does the purchase take?
30–45 days from reservation to title registration. We handle the paperwork.
Q: Can I visit before buying?
Yes. We arrange 2–3 day site visits including airport pickup, hotel, and compound tours. Cost: €350/person (deducted from purchase if you proceed).
Q: What’s the exit strategy if I want to sell?
MAMO can broker resale through our network. Typical time-to-sale: 3–6 months at 5–10% below current market for quick sale, or 1–2% below market for premium positioning.
Sources: MAMO Property managed portfolio data 2024–2026, Cairo Developments Association Q1 2026 report, Egyptian Real Estate Authority transaction registry (publicly aggregated).
This article is editorial analysis, not investment advice. Past performance does not guarantee future results. Real estate investment carries market, currency, and operational risk.
MAMO Property — Your Gateway to Red Sea Real Estate
Since 2008 | Licensed Egyptian brokerage | Multilingual team EN/AR/DE/PL/CS/RU
WhatsApp: +20 115 298 0998 | Web: mamoproperty.com
Co-founder of MAMO Property, real estate specialist in Hurghada with 16+ years experience in Egyptian property market.